Cashless health insurance can make hospitalisation easier to manage by reducing the need to arrange the entire eligible treatment amount upfront. Instead, the insurer or its authorised claims administrator coordinates directly with a network hospital for admissible medical expenses.
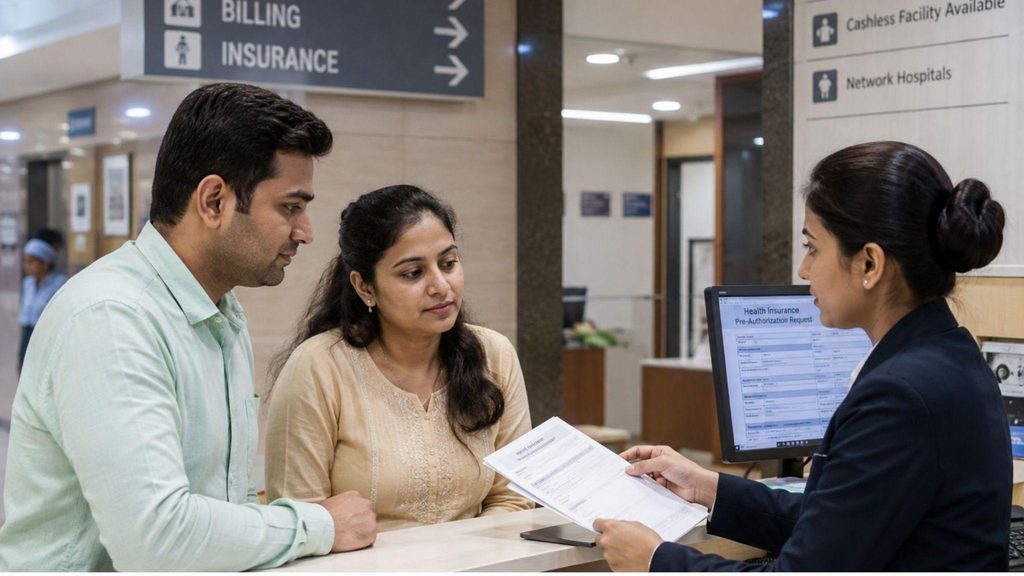
However, cashless treatment involves more than simply presenting an insurance card at admission. Understanding network hospitals, pre-authorisation and final claim approval can help policyholders know what to expect and complete the required steps with greater confidence during hospitalisation.
What Is Cashless Health Insurance?
Cashless health insurance is a claim facility through which eligible hospitalisation expenses are settled directly between the insurer and an empanelled hospital, subject to policy terms and claim assessment.
This facility can be particularly useful in cities with extensive healthcare networks, where the best health insurance in Delhi for individual needs may include access to suitable network hospitals for planned as well as emergency treatment.
The insured person completes the required cashless formalities while the hospital coordinates the claim process with the insurer.
How Network Hospitals Enable Cashless Treatment
Network hospitals are healthcare facilities that have arrangements with an insurer or its authorised administrator for processing eligible cashless claims. They form an important part of the cashless system because claim-related information can be exchanged directly between the hospital and insurer.
Policyholders can generally:
- Check whether the chosen hospital is part of the insurer’s current network.
- Approach the hospital’s insurance or cashless helpdesk.
- Provide policy and identity details as required.
- Complete the necessary claim-related forms and documentation.
What Is Pre-authorisation in Cashless Claims?
Pre-authorisation is the initial request sent by the network hospital to the insurer or claims administrator seeking approval for cashless treatment. It usually contains relevant medical details, the proposed treatment, hospital information and an estimated treatment expense.
The insurer reviews the submitted information against the applicable policy terms before communicating its decision. Pre-authorisation is therefore an important stage in a cashless claim, but it should not be understood as automatic or unconditional approval of every expense incurred during hospitalisation.
How the Pre-Authorisation Process Works
The process usually begins after the hospital receives the patient’s insurance information. For a planned hospitalisation, formalities may be initiated before admission. For an emergency, the hospital can begin the process after the patient has been admitted, subject to the insurer’s applicable procedure.
The process may involve:
- Submission of a cashless request by the network hospital.
- Review of medical and policy information.
- Requests for additional documents or clarification where required.
- Communication of the initial cashless decision to the hospital.
What Happens after Pre-authorisation Approval?
Once pre-authorisation is approved, treatment can proceed under the cashless arrangement within the approved terms. The hospital continues recording treatment details and expenses during the patient’s stay. Approval at this stage does not necessarily represent the final amount that will be settled.
During hospitalisation:
- Medical records are updated as treatment progresses.
- Additional authorisation may be requested if the treatment plan changes.
- The hospital may share revised medical information with the insurer.
- The final claim remains subject to assessment under the policy terms.
How Final Approval Is Given at Discharge
Final cashless approval generally takes place around the time of discharge. The hospital prepares the final bill along with the discharge summary and supporting medical documents and submits them for claim assessment. The insurer or claims administrator reviews the final information and determines the admissible amount according to the applicable policy conditions.
The process generally includes:
- Submission of the final hospital bill.
- Review of treatment and medical documents.
- Assessment of eligible expenses.
- Communication of the approved amount to the hospital.
- Completion of the discharge-related cashless formalities.
Read Also: Government Reduces GST to 0% on Term and Health Insurance Policies: Key Features & Major Benefits
What Happens if Cashless Approval Is Delayed or Rejected?
A cashless decision may require additional time when further medical information, documentation or clarification is needed. A request may also not receive approval where the claim does not meet the applicable conditions for cashless processing. This does not necessarily mean that every possibility of making a claim ends.
Policyholders can:
- Ask the hospital helpdesk about the current claim status.
- Provide additional documents requested during assessment.
- Contact the insurer for clarification about the decision.
- Understand whether reimbursement can be considered according to policy terms.
- Keep original bills, reports and supporting documents safely.
Expenses You May Still Need to Pay Personally
Cashless treatment does not always mean that no payment will be required from the policyholder. The insurer settles expenses that are considered admissible under the health insurance policy, while other amounts may remain payable by the insured person.
These may include:
- Expenses outside the scope of the approved claim.
- Applicable deductibles or co-payment amounts.
- Charges exceeding eligible policy limits, where relevant.
- Personal or non-medical expenses not forming part of the admissible claim.
- Differences between the final hospital bill and the amount approved under the policy.
Conclusion
Cashless health insurance can simplify the financial administration of hospitalisation, but the process involves several connected stages. Network hospital verification, pre-authorisation, ongoing communication during treatment and final approval at discharge each play an important role. Understanding these steps helps policyholders approach hospitalisation with better awareness of their responsibilities and the insurer’s assessment process.
Hi, I’m Dev Kirtonia, Founder & CEO of Dev Library. A website that provides all SCERT, NCERT 3 to 12, and BA, B.com, B.Sc, and Computer Science with Post Graduate Notes & Suggestions, Novel, eBooks, Biography, Quotes, Study Materials, and more.
Subject Ka Complete Video Solution Dekhein
Step-by-step easy concept explanation aur full questions Answer ke liye watch karein ya app download karein:
 Buy Now